The women’s fashion and styling sector in Bangladesh is undergoing a historic shift. Driven by e-commerce adoption, rising disposable income, and a surge of female entrepreneurs, homegrown apparel brands, boutique houses, and styling studios are scaling rapidly. However, transitioning from a boutique studio or online shop into a recognized commercial brand requires capital. Whether expanding your inventory for Eid, opening a physical outlet in Dhanmondi or Banani, or setting up a dedicated manufacturing unit, securing an Small and Medium Enterprise (SME) loan is often the single most effective way to scale.
Despite dedicated financial incentives introduced by Bangladesh Bank—including concessionary interest rates for women entrepreneurs—navigating the formal banking and Non-Bank Financial Institution (NBFI) loan application process can feel daunting.
This comprehensive guide details everything you need to know about applying for an SME loan in Bangladesh, specifically tailored to fashion, styling, and apparel retail businesses.
Understanding SME Financing in Bangladesh’s Fashion Industry
In Bangladesh, the Central Bank defines Small and Medium Enterprises based on asset size, annual turnover, and employee count. In fashion retail, service, and apparel manufacturing, businesses generally fall under Cottage, Micro, or Small Enterprises (CMSME).
┌─────────────────────────────────────────────────────────────────────────────┐
│                       CMSME CLASSIFICATION (BANGLADESH BANK)               │
├─────────────────────────┬──────────────────────────┬────────────────────────┤
│ Enterprise Type         │ Sector                   │ Typical Funding Range  │
├─────────────────────────┼──────────────────────────┼────────────────────────┤
│ Micro Enterprise        │ Service / Trading        │ BDT 5 Lac - 50 Lac     │
│ Small Enterprise        │ Retail / Manufacturing   │ BDT 50 Lac - 2 Crore   │
│ Medium Enterprise       │ Garment/Textile Production│ BDT 2 Crore - 15 Crore  │
└─────────────────────────┴──────────────────────────┴────────────────────────┘
Why SME Loans Are Ideal for Fashion & Styling Enterprises
Unlike equity dilution or informal borrowing from friends and family, formal SME financing provides structured, predictable growth capital with distinct advantages:
-
Lower Interest Rates for Female Entrepreneurs: Bangladesh Bank mandates specific refinance schemes for women entrepreneurs. Women-led fashion businesses can access SME loans at subsidized interest rates (as low as 5% to 7% per annum through Bangladesh Bank refinancing programs).
-
Unsecured / Collateral-Free Limits: Banks offer collateral-free SME loans up to BDT 25 Lacs to BDT 50 Lacs under specialized women’s entrepreneur schemes.
-
Working Capital Financing: Ideal for fashion brands that experience intense seasonal cash flow cycles around major festivals like Eid-ul-Fitr, Pahela Baishakh, and wedding seasons.
Key Takeaway: A woman-led fashion brand registered in Bangladesh can access up to BDT 50 Lacs in collateral-free funding if the business maintains clean trade licensing, proper tax documentation, and transparent bank transaction histories.
Essential Eligibility Criteria for Fashion & Retail Businesses
Before submitting an application, verify that your fashion enterprise meets the standard eligibility thresholds established by Bangladeshi commercial banks (e.g., BRAC Bank, Eastern Bank PLC, City Bank PLC, IPDC, IDLC).
                     ┌───────────────────────────────────────┐
                     │ 1. Business Age (Min 1-2 Years)        │
                     └───────────────────┬───────────────────┘
                                         │
                                         ▼
                     ┌───────────────────────────────────────┐
                     │ 2. Valid Trade License & e-TIN        │
                     └───────────────────┬───────────────────┘
                                         │
                                         ▼
                     ┌───────────────────────────────────────┐
                     │ 3. Age Limit (21 - 65 Years)           │
                     └───────────────────┬───────────────────┘
                                         │
                                         ▼
                     ┌───────────────────────────────────────┐
                     │ 4. Clean CIB (Credit Information) Report│
                     └───────────────────────────────────────┘
-
Length of Continuous Operation:
-
General Applicants: Minimum 2 years of continuous business operations.
-
Women Entrepreneurs: Minimum 1 year of continuous operation (under special women’s development programs).
-
-
Legal Entity Status: Sole proprietorship, partnership firm, or private limited company.
-
Applicant Age Limit: Usually between 21 and 65 years.
-
Credit History (CIB Status): Clean report from the Credit Information Bureau (CIB) of Bangladesh Bank, ensuring no prior personal or business loan defaults.
Step-by-Step SME Loan Application Process
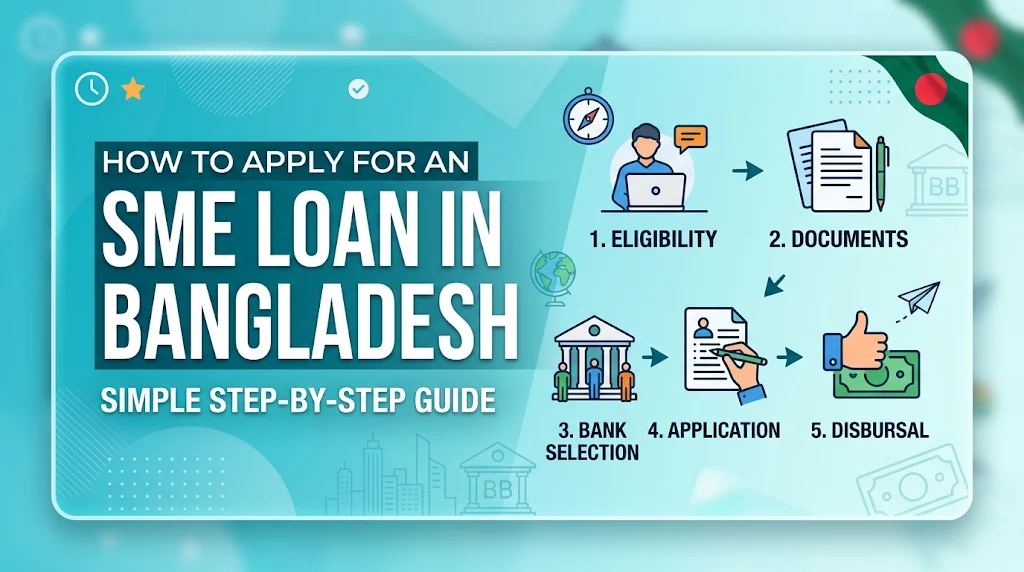
┌─────────────────────────────────────────────────────────────────────────────┐
│                         SME LOAN APPLICATION ROADMAP                        │
├──────────────┬──────────────────────────────────────────────────────────────┤
│ Phase 1      │ Document Preparation & Legal Setup                           │
│ Phase 2      │ Bank / Financial Institution Selection                       │
│ Phase 3      │ Business Proposal & Financial Projection Draft               │
│ Phase 4      │ Verification, Field Visit & Approval                         │
│ Phase 5      │ Disbursement & Utilization Documentation                     │
└──────────────┴──────────────────────────────────────────────────────────────┘
Step 1: Legal & Documentation Readiness
Proper documentation is the single most crucial factor in securing loan approval. Gather and organize the following files:
General & Legal Documents:
-
Updated Trade License: Issued by the respective City Corporation or Union Parishad.
-
National ID (NID) Cards: Copies for owner(s) and guarantors.
-
Passport-sized Photographs: 3–4 copies of the applicant and guarantors.
-
e-TIN & Recent Tax Return Certificate: Copy of electronic TIN and latest tax acknowledgement slip (e.g., IT-10B statement).
-
Business Premises Proof: Rent agreement deed or property ownership document for the store, studio, or factory space.
-
Partnership Deed / Memorandum of Association: Required if operating as a partnership firm or registered Private Limited Company.
Financial & Operational Documents:
-
Bank Statements: Last 12 months of official bank statements reflecting business turnover.
-
Financial Statements: Balance sheet, profit & loss statement, and cash flow statement for the past 1 to 2 years (audited if applying as a Limited Company).
-
Supplier & Client Invoices: Proof of active trade transactions with fabric suppliers, weavers, or retail clients.
Step 2: Select the Right Bank & Specialized Scheme
Choose a financial institution offering dedicated SME products tailored to fashion enterprises and women entrepreneurs:
┌─────────────────────────────────────────────────────────────────────────────┐
│                  TOP SME LOAN SCHEMES IN BANGLADESH (OVERVIEW)              │
├──────────────────┬─────────────────────────────┬────────────────────────────┤
│ Bank / NBFI      │ Specialized Scheme          │ Highlights                 │
├──────────────────┬─────────────────────────────┬────────────────────────────┤
│ BRAC Bank        │ TARA Uddokta Loan           │ 5% Interest, Collateral-   │
│                  │                             │ free options for women  │
├──────────────────┬─────────────────────────────┬────────────────────────────┤
│ Eastern Bank PLC │ EBL Mukti / EBL Utkorsho    │ Quick processing, minimum  │
│                  │                             │ documentation          │
├──────────────────┬─────────────────────────────┬────────────────────────────┤
│ IDLC Finance     │ IDLC Purnony / New Entrant  │ Subsidized rates, business │
│                  │                             │ advisory services         │
├──────────────────┬─────────────────────────────┬────────────────────────────┤
│ City Bank PLC    │ City Alo Women's Banking    │ Customized tenure & soft   │
│                  │                             │ collateral options         │
└──────────────────┴─────────────────────────────┴────────────────────────────┘
Pro Tip for Fashion Brands: Prioritize banks that offer Revolving Credit (RC) or Overdraft (OD) facilities alongside standard Term Loans. Overdraft facilities allow fashion brands to draw cash quickly to purchase raw fabrics during seasonal rushes and repay immediately as sales roll in during Eid or wedding seasons.
Step 3: Prepare a Targeted Business Plan & Investment Statement
Financial officers look closely at how the loan capital will generate returns. Your proposal should address the unique cash flow dynamics of the women’s fashion industry:
-
Clear Purpose of Funds: Specify whether the money will be used for buying inventory (fabric, embellishments), purchasing machinery (sewing machines, embroidery tools), digital marketing campaigns, or opening a retail showroom.
-
Seasonal Revenue Breakdown: Illustrate how sales peak during major festive seasons (Eid-ul-Fitr, Pahela Baishakh, Durga Puja, and winter wedding months).
-
Repayment Capacity: Show that regular monthly cash flows (from off-season sales and everyday styling services) comfortably cover the Monthly Equated Installment (EMI).
Step 4: Credit Verification & Physical Premises Audit
Once your formal application is submitted, the financial institution conducts an inspection:
-
Physical Site Visit: Bank officers visit your boutique showroom, online fulfillment hub, or manufacturing workshop to verify inventory levels and operations.
-
CIB Inquiry: Bangladesh Bank evaluates your individual and corporate credit history.
-
Guarantor Assessment: Most unsecured SME loans require 1 to 2 personal guarantees (often family members or established business figures).
Step 5: Loan Sanction & Disbursement
Upon approval, the bank issues a Sanction Letter detailing:
-
Approved loan amount and applicable interest rate.
-
Tenor (typically 12 to 60 months).
-
Schedule of monthly installments and processing fees (plus applicable VAT).
After signing the acceptance letter and completing documentation (such as promissory notes or hypothecation of inventory), the funds are disbursed directly into your business bank account.
Common Pitfalls to Avoid When Applying for SME Funding
┌─────────────────────────────────────────────────────────────────────────────┐
│                         COMMON APPLICATION PITFALLS                         │
├──────────────────────────────────────┬──────────────────────────────────────┤
│ ❌ Pitfall                           │ ✅ Solution                          │
├──────────────────────────────────────┼──────────────────────────────────────┤
│ Mixing Personal & Business Funds     │ Maintain a separate business account  │
│ Expired Trade License                │ Renew licenses prior to application  │
│ Overestimating Cash Flow             │ Present conservative, realistic P&L  │
│ Unregistered Business Name           │ Ensure all documents share matching  │
│                                      │ legal entity names                   │
└──────────────────────────────────────┴──────────────────────────────────────┘
-
Commingling Business and Personal Finances: Depositing boutique revenue into a personal savings account obscures your true business turnover, making bank officers hesitant to approve larger loan amounts.
-
Inconsistent Entity Names: Ensure your Trade License, e-TIN, bank account, and shop rental agreement reflect the exact same business name.
-
Under-documenting Offline Sales: Many online fashion pages accept cash on delivery (COD) or mobile financial services (MFS) payments (e.g., bKash, Nagad). Ensure MFS revenues are routinely transferred into your official business bank account to build a verified transaction history.
Checklist: Essential Documents for Your SME Application
Ensure you have all items completed before visiting your financial institution:
Frequently Asked Questions (FAQs)
Can I get an SME loan for an online-only fashion page (F-commerce)?
Yes. While traditional banks prefer a physical outlet, many financial institutions (including BRAC Bank, IPDC, and IDLC) offer specialized CMSME financing to registered digital/e-commerce businesses. You must present an up-to-date Trade License listing online retail, a clear transaction history via MFS/bank accounts, and verifiable sales records.
What interest rate can female fashion entrepreneurs expect in Bangladesh?
Under Bangladesh Bank refinance schemes for women entrepreneurs, eligible female-led businesses can access loans at concessionary interest rates of around 5% to 7% per annum. Standard commercial SME interest rates generally range higher depending on current market yield rates and bank policies.
Is collateral always mandatory for an SME loan?
No. Under Bangladesh Bank guidelines and dedicated women’s entrepreneur schemes, banks can provide unsecured (collateral-free) SME loans up to BDT 25 Lacs to BDT 50 Lacs. However, personal guarantees and hypothecation of business inventory or equipment are typically required.
Conclusion & Next Steps
Securing an SME loan can be a major milestone for your fashion, styling, or retail enterprise in Bangladesh. By organizing your legal documents, keeping clean bank records, and taking advantage of dedicated refinancing schemes for women entrepreneurs, you can secure the working capital needed to expand your inventory, scale production, and launch your next collection.

Author: Nasir Uddin
Nasir Uddin is a dedicated writer and researcher at BanglaLook.com, where he explores topics related to education, Bangladeshi culture, lifestyle, and travel. With a strong passion for learning and storytelling, he blends personal observation with well-researched insights to help readers better understand Bangladesh and the world around them.